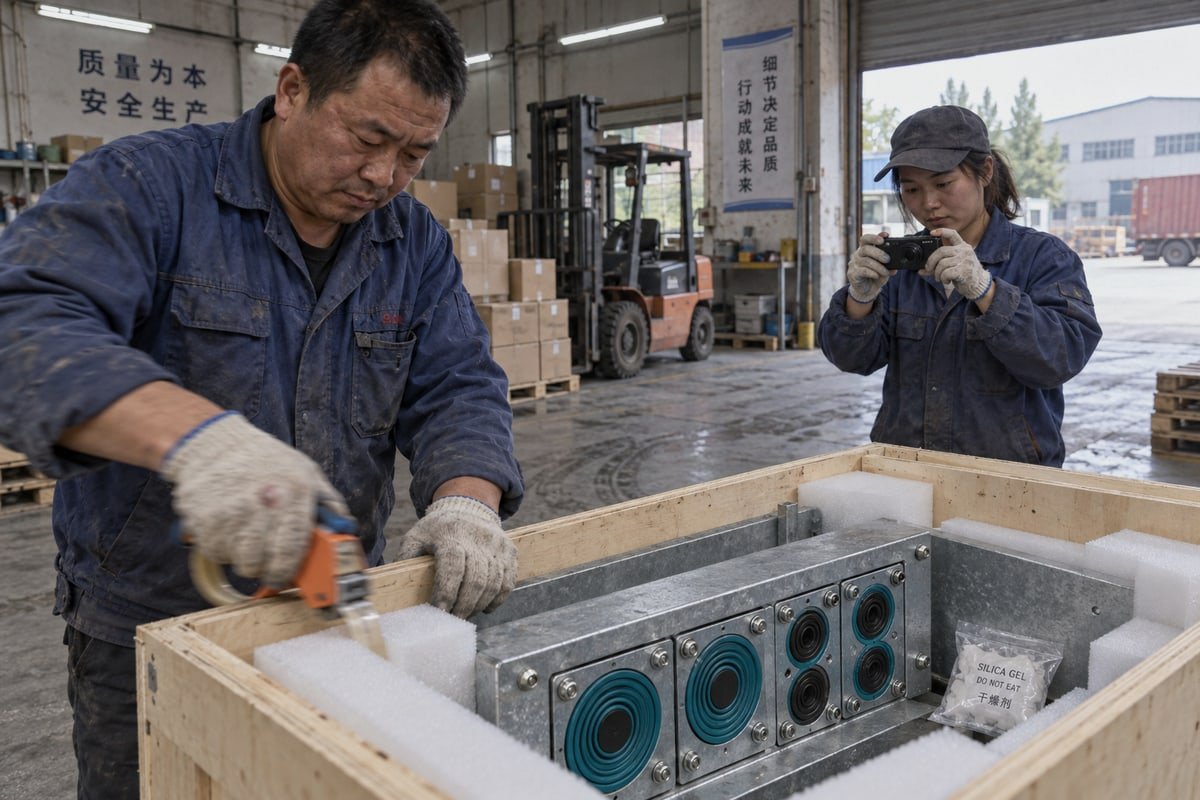
Every month our export desk ships MCT modules overseas, and buyers keep asking me the same worrying question: cargo insurance vs performance bonds — which risks does each actually cover?
Cargo insurance covers physical loss or transit damage to the multi cable transits themselves—crushing, theft, water ingress, fire, general average. A performance bond covers supplier default: late delivery, non-conforming specs, missing certifications, or insolvency. Insurance protects the goods; the bond protects the contract. Most project importers need both.
The confusion is not harmless. I have seen buyers assume a bond would pay for a crushed crate. I have seen others assume an [insurance certificate](https://dewinmct.com/?p=821) would get a shipment through customs clearance. Both assumptions fail at the worst moment: when a BESS container or a switchgear line is waiting for cable sealing systems. Below, I break down what each tool does, where each one stops, and what paperwork you should collect from your supplier before the first crate leaves our loading bay.
Which risks does cargo insurance actually cover when I import MCT sealing modules from overseas?
Last year one of our TSC module crates reached Rotterdam with a forklift tine through the side. That claim taught our packing team more than any textbook.
Cargo insurance covers physical loss or damage to your MCT sealing modules while in transit: crushing, drops, theft, fire, seawater, vessel collision, and general average contributions. Under Institute Cargo Clauses A it is all-risks. It excludes inherent vice, poor packing, delay, and supplier default.
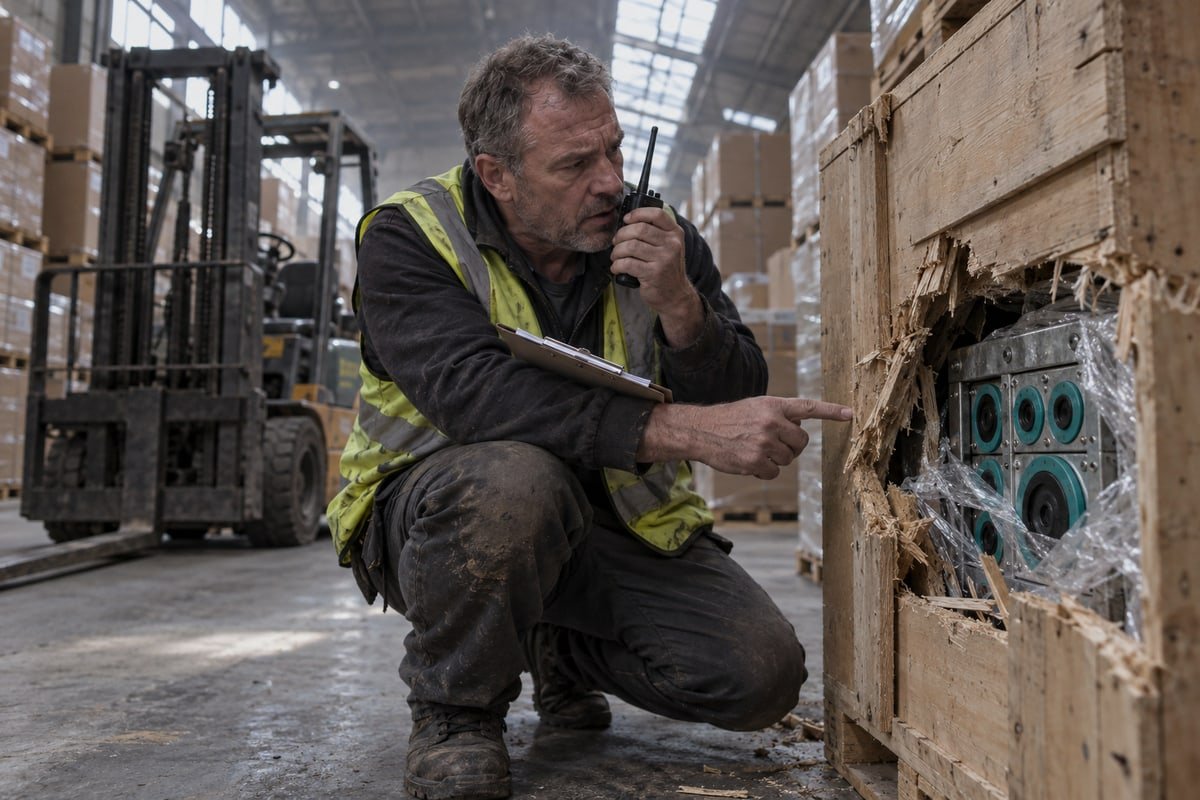
Marine cargo insurance is a two-party contract. You (or the seller, depending on Incoterms) pay a premium. The insurer absorbs the financial loss if an insured peril 1 damages the goods. That is the whole deal. The insurer does not care whether our modules meet your spec. It only cares whether they arrived in the same physical condition they left in.
Named perils vs all risks
Most policies on industrial components are written on one of three standard wordings. The differences matter for a crate of EPDM sealing modules and galvanized frames.
| Clause set | Coverage basis | Typical use for MCT shipments |
|---|---|---|
| Institute Cargo Clauses A | All risks, except listed exclusions | Full container or LCL shipments of frames, compression units, and modules |
| Institute Cargo Clauses B | Named perils, including water entry into hold or container | Lower-value spare module orders |
| Institute Cargo Clauses C | Major casualties only: fire, collision, vessel stranding | Minimum cover a seller must provide under CIF or CIP |
I tell buyers to ask for Clauses A. Forklift damage at a transshipment port is not a "major casualty," so Clauses C would not respond. Clauses A would.
General average
This is the risk most engineering buyers have never heard of. If a vessel has a fire and the master jettisons containers to save the ship, every cargo owner on board must share the cost. The shipping line will hold your undamaged MCT modules until you post an average bond 2 or cash deposit. With cargo insurance, the insurer issues the guarantee. Without it, your project cash is tied up while the adjusters work, and general average cases can run for months.
Exclusions that matter for EPDM modules
Our modules use halogen-free, step-core EPDM rubber. It is stable across a wide temperature range, but no elastomer is immune to abuse. Insurers exclude "inherent vice," meaning natural degradation of the goods themselves. If a container sits on a hot quay for weeks and a competitor's low-grade rubber hardens, the insurer may argue that was inherent vice, not an external peril. They also exclude insufficient packing. That is why we photograph every crate, desiccant pack, and corner brace before sealing.
Cargo insurance also excludes delay. A late vessel that pushes your commissioning date costs you money, but a standard policy pays nothing. I return to that gap in the decision section.
What risks do performance bonds cover that cargo insurance leaves out on my MCT orders?
A German BESS integrator once asked our sales engineer for a bond before placing a first order. I understood why. They had been burned by a supplier who vanished mid-project.
A performance bond is a financial guarantee from a surety that the MCT supplier will perform the contract. It covers late delivery, wrong specifications, missing ATEX, IECEx or DNV certificates, dimensional incompatibility, warranty defects, and supplier insolvency—none of which cargo insurance pays for.
The fastest way to see the split is side by side. Here is how I explain cargo insurance vs performance bonds to a purchasing engineer who reads spec sheets before replying.
| Risk event on an MCT order | Cargo insurance | Performance bond |
|---|---|---|
| Crate crushed at port | Pays | No |
| Container stolen from yard | Pays | No |
| Supplier ships modules 6 weeks late | No | Pays liquidated damages up to bond value |
| Modules lack required hazardous-area certificate | No | Pays cost to re-source |
| Modules do not fit existing 120-frame cutouts | No | Pays cost to correct or replace |
| Seal fails in warranty period from manufacturing defect | No | Pays if bond includes maintenance period |
| Supplier goes insolvent after deposit | No | Pays deposit recovery and re-sourcing |
| Customs holds shipment for unpaid duty | No | Customs bond, not performance bond |
A three-party structure, not insurance
A surety bond has three parties: the supplier (principal), you (obligee), and the surety. If we fail to perform, the surety pays you, then seeks reimbursement from us. That last step changes behaviour. A supplier who has signed a bond has real skin in the game. Cargo insurance, by contrast, is a two-party risk transfer with no recourse against the supplier.
Some brokers describe bonds as "performance insurance." I push back on that. A bond does not indemnify you for shipment damage. It guarantees an obligation. That is a legal difference, not a marketing one.
Performance bond vs customs bond
Buyers often merge these two. Both sit under the broad surety category, but they serve different obligations. A customs bond guarantees payment of duties, taxes, and fees to the importing authority. In the United States, CBP requires one when goods enter above value or regulatory thresholds, and a continuous transaction bond 3 can cover all shipments imported during one year. A performance bond guarantees the supplier's contract obligations to you. Tariff volatility has made customs bond amounts more sensitive, but that does not make the customs bond a substitute for a performance bond.
Certification and interoperability risk
Two bond clauses matter specifically for cable sealing systems. First, certification risk: if your hazardous-area project 4 requires ATEX, IECEx, or DNV ratings and the delivered units lack them, the bond funds an alternative source. Second, interoperability risk: on a retrofit, modules that do not match existing frame cutouts are scrap. Our TSC and TSR series are dimensionally compatible with common 120-frame standards, and we back that with cross-reference tables and free validation samples. A bond that references those samples gives you a clean, testable performance standard.
How do I decide whether I need cargo insurance, a performance bond, or both for my MCT shipments?
Cost is the trade-off we weigh with buyers every week. A bond adds a fee to a module order that already saves them 40–60%. So does it still make sense?
Buy cargo insurance on every MCT shipment where you carry transit risk under your Incoterms. Add a performance bond when the order is project-critical, the supplier is new, liquidated damages apply, or certification is mandatory. Use both when a customs hold or supplier default costs more than the goods.
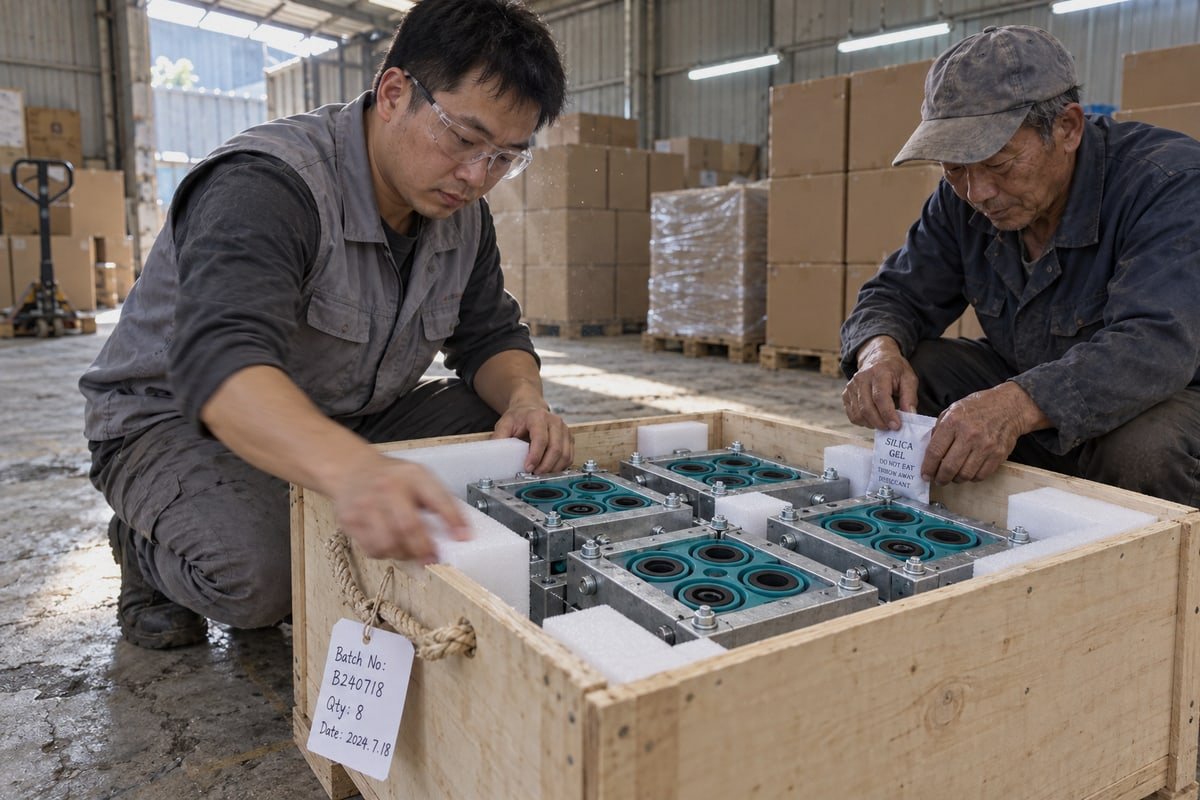
I use a simple four-step process with procurement teams. It fits into any supply chain risk management review.
- Check your Incoterms. Under EXW or FOB, transit risk passes to you at our factory gate or the ship's rail. You must buy the marine cargo insurance. Under CIF or CIP, we buy it, but only to the minimum clause level unless you specify Clauses A in the purchase order.
- Value the delay, not just the goods. A crate of sealing modules may be a small line item. The data center it seals is not. If lost transit seals stall commissioning, the project delay penalties can exceed the invoice many times over. A standard policy will not pay them. Ask for a Delay in Start-Up rider, or accept that risk knowingly.
- Score the supplier. A first order from an unknown factory carries supplier default risk. A repeat order from a supplier with ISO 9001 5, IATF 16949, and a BV-approved factory carries less. A bond makes sense in the first case. It may be optional in the second.
- Check the contract. If your EPC customer applies liquidated damages to you, pass a matching performance bond requirement down to your MCT supplier.
Scenario matrix
| Order type | Cargo insurance | Performance bond | Notes |
|---|---|---|---|
| Spare module replenishment, repeat supplier | Yes | Usually no | Low value, short lead time |
| First qualification order with validation samples | Yes | Optional | Low value; samples are free anyway |
| Full frame set for new BESS container line | Yes, Clauses A | Yes | Delay hits production schedule |
| Retrofit into existing frames on an offshore platform | Yes, plus DSU rider | Yes, with interoperability clause | Wrong dimensions equal scrap |
| Hazardous-area switchgear project requiring certificates | Yes | Yes, with certification clause | Certification failure blocks approval |
The buyer objection I hear most
"If I only care about the crate arriving intact, insurance is enough." That is true for the crate. It is not true for the transaction. Customs clearance problems, missing test documents, or a supplier who misses the date are not transit events. I have watched an importer with perfect cargo cover lose weeks because a duty guarantee was not in place. The goods were fine. The project was not. That is why I treat cargo insurance vs performance bonds as complementary, not competing.
What documentation should I request from my MCT supplier to support an insurance or bond claim if something goes wrong?
One lesson from a decade of exporting cable sealing systems: a claim is only as strong as its paper trail. So we build the file before the crate closes.
Request the commercial invoice, packing list, bill of lading, insurance certificate, packing photos, and pre-shipment inspection report to support a cargo claim. For a bond claim, keep the signed contract, bond wording, delivery schedule, certificates such as ATEX or DNV, test reports, and written notices of default.
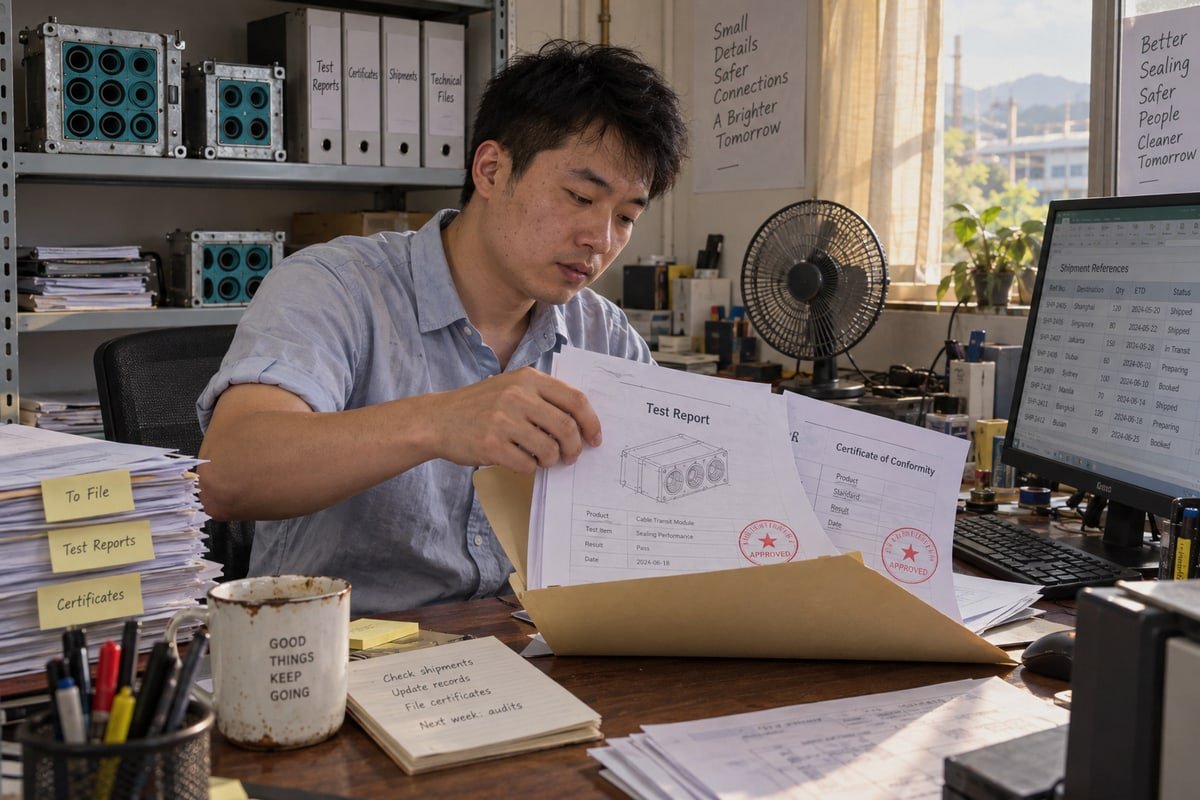
Insurers and sureties both reject claims for the same reason: gaps in evidence. The good news is that most of the evidence should already exist if your supplier handles export documentation properly. Our export desk prepares the full set for every shipment, and I recommend you ask any supplier to do the same.
Documents by claim type
| Document | Cargo claim | Bond claim | Who provides it |
|---|---|---|---|
| Commercial invoice and packing list | Required | Required | Supplier |
| Bill of lading or air waybill, clean and unclaused | Required | Supporting | Carrier via supplier |
| Insurance certificate naming the assured | Required | No | Whoever bought cover |
| Timestamped packing and container loading photos | Required | Supporting | Supplier |
| Pre-shipment inspection or QC report | Required | Required | Supplier or third party |
| Survey report at destination | Required | No | Independent surveyor |
| Signed contract with delivery dates and spec | Supporting | Required | Both parties |
| Bond wording and surety contact | No | Required | Supplier's surety |
| Test documents: fire rating A-0/A-60, IP68, gas-tight 0.01–0.4 MPa | No | Required | Supplier |
| Hazardous-area certificates where specified | No | Required | Supplier |
| Written notice of default with cure period | No | Required | Buyer |
Timing rules that kill claims
For transit damage, note the damage on the delivery receipt before you sign. Photograph the crate before you open it. Notify the insurer and the carrier in writing within days, not weeks. Request a survey while the packaging is still in your warehouse. If you discard the crate, you discard your evidence.
For a bond claim, the sequence is different. You must first notify the supplier of the default in writing and allow the cure period the contract specifies. Only then can you call on the surety. Keep every email about delivery dates and specification changes. A surety will read them all.
What we hand over as standard
I am direct with buyers about this because it is where a factory-direct supplier earns trust. Our test documents for fire rating, ingress protection, and pressure sealing are available on request before the order, not after a dispute. Our cross-reference tables show which existing model each DEWIN module replaces, which gives a bond claim a clear compatibility benchmark. And because we make our own molds in-house, we can document custom sizes with drawings and STEP files that match the physical part. That is the evidence a claims adjuster wants to see.
Fazit
Confusion here costs real money. Insure the goods, bond the contract, and file the paperwork early. Then your MCT import is protected from the crate to the commissioning date.
Fußnoten
1. Definition of specific risks covered under marine insurance contracts. ↩︎
2. Legal guarantee required to release cargo under general average maritime law. ↩︎
3. Official CBP definition of bonds covering multiple import entries over a year. ↩︎
4. Global certification body for equipment used in explosive environments. ↩︎
5. International standard for quality management systems and manufacturing consistency. ↩︎



 English
 Español de México
 Deutsch
 Français
 العربية
 Русский