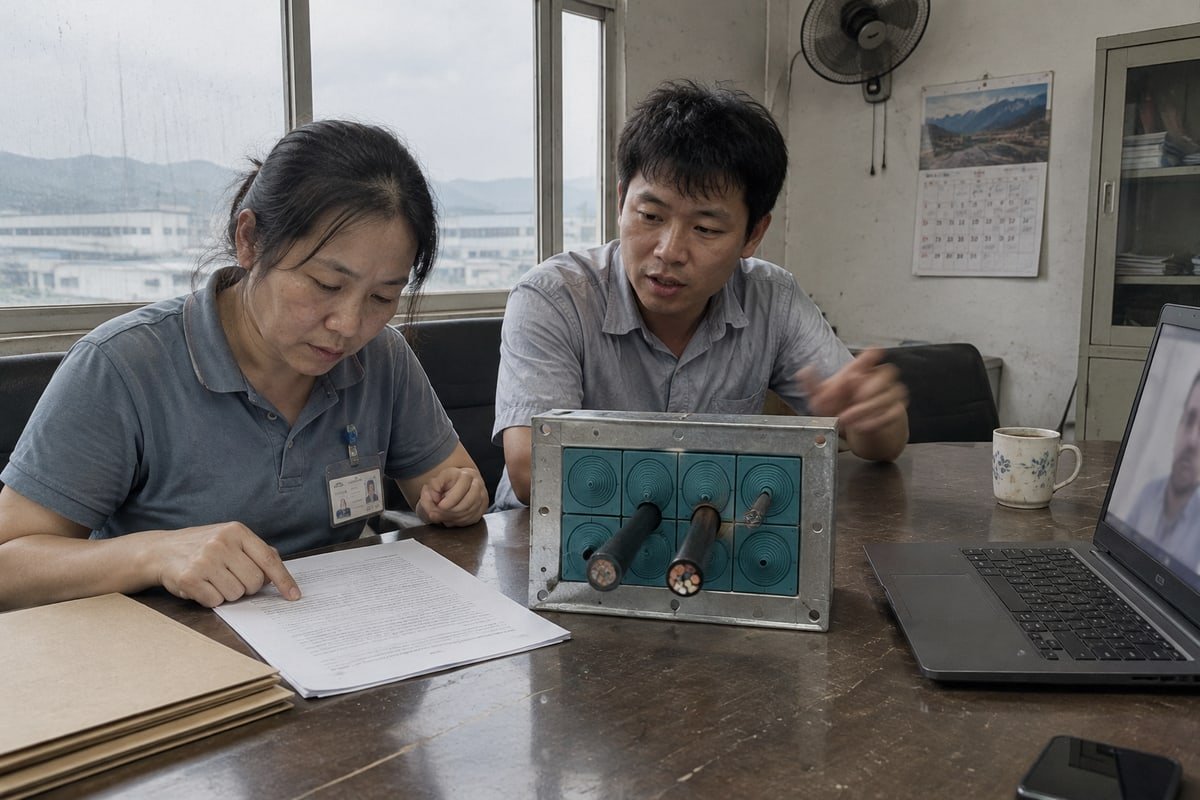
Procurement costs for multi cable transits 1 rarely stay where the budget put them. Buyers our factory supplies watch FX and steel eat margin before PO. It is fixable.
To lock in procurement costs for multi cable transits, fix the known part with 12–24 month framework agreements, index the unknown part to steel and rubber, hedge residual currency with forward contracts, and qualify a certified drop-in second source to keep pricing competitive.
The rest of this article walks through that playbook in order. I start with hedging, move to contract structures, then cover supplier validation, and finish with the documents you should demand.
How can I hedge against currency and material price swings when sourcing MCT systems internationally?
A European sourcing manager once asked me to hold a EUR quote for 90 days. Our EPDM and galvanized steel costs shifted well before the PO arrived.
Hedge MCT sourcing by mapping exposure first, then combining tools: forward exchange contracts for firm payables, options for uncertain volumes, natural hedging where you hold matching currency inflows, functional-currency invoicing from the supplier, and raw material price indexation for steel and EPDM inputs.
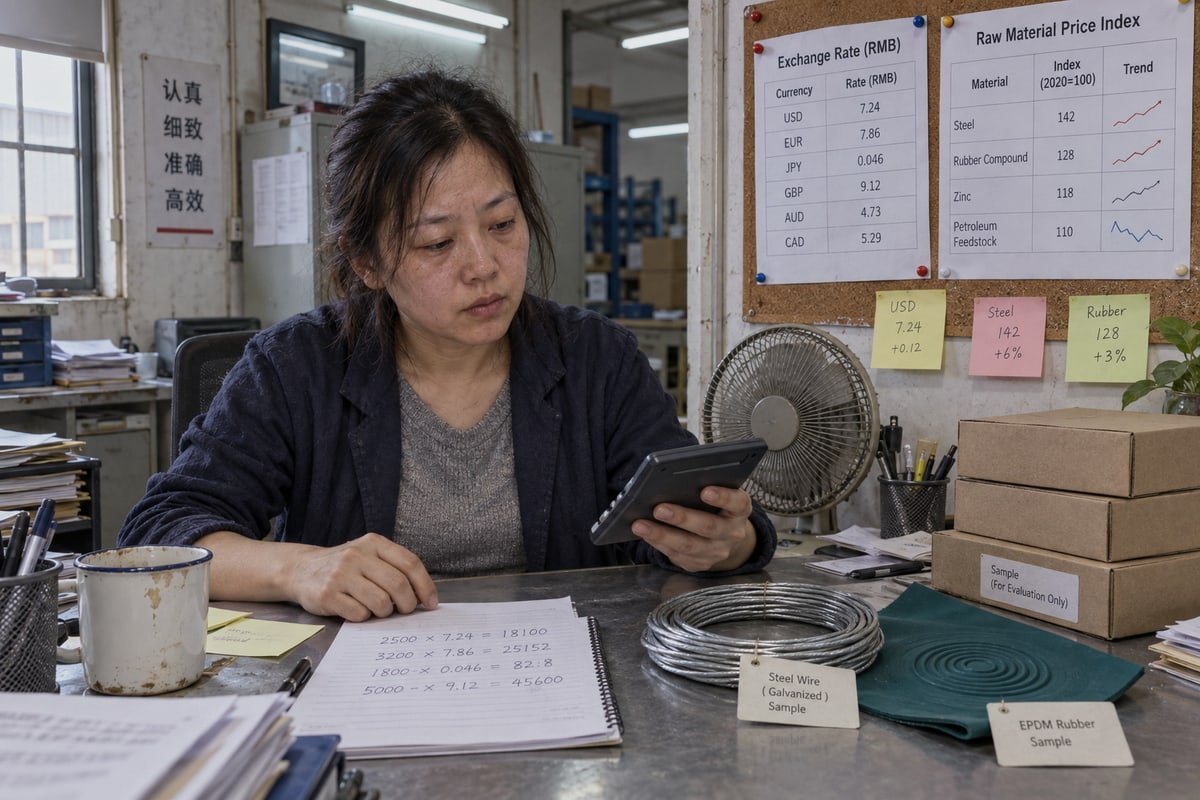
That 90-day request taught me something. The buyer was not being difficult. He simply had no map of where his cost could move. So we built one together. It had two legs: the supplier-side material leg and the currency leg. Each leg needs a different tool.
Start with the three exposure types
Before you pick a hedge, decide what kind of exposure you are holding. Treasury teams usually split it three ways.
| Exposure type | What it means for MCT buying | Best-fit tool |
|---|---|---|
| Transaction exposure | A confirmed PO in USD or RMB with a known payment date | Forward exchange contract |
| Budget exposure | Forecast spend for a BESS or data center program that may still change | Options or collars, shorter quote validity |
| Structural exposure | Repeated annual spend on modular cable seals across many projects | Formal hedging policy, netting, natural hedging |
Most of my customers only hedge the first row. That is fine for a single frame order. It is not enough for a multi-year program.
Currency hedging strategies in plain language
A forward contract locks a future exchange rate for a payable you already know. It is cheap and simple. Options and collars cost a premium, but they cap the downside while keeping some upside. They suit projects where volume or timing is still open. Natural hedging works when your group already earns in the supplier's currency, so the net exposure shrinks. Netting and treasury centralization help groups with several plants buying in the same currency.
The simplest lever is often overlooked. Ask the supplier to invoice in your functional currency. Our export team quotes in EUR or USD for European and Middle East buyers when the payment window is short. That moves part of the risk to our side, and we manage it through our own supply chain risk mitigation.
Is hedging overused?
Some procurement teams push back. They say hedging adds cost, paperwork, and mark-to-market noise. That objection is fair when volumes are vague. It falls apart when the payable is firm and the margin is thin. Industrial commodity inputs have shown 10–20% annualized volatility in recent years. On a fixed-price EPC contract 2, doing nothing can cost more than the hedge. Some companies now hedge three to five years forward for exactly this reason. My rule is simple: contract first, net second, and hedge only the residual.
What contract structures let me lock in unit pricing for cable transit modules over a multi-year project?
Every fixed-price request lands on my desk as a trade-off: hold TSC module pricing for 24 months, or protect our margin if EPDM compound 3 jumps. Both sides need a formula.
Lock unit pricing for cable transit modules with a 12–24 month framework procurement contract that fixes the base price, adds a transparent steel and rubber index formula with a threshold band, shortens quote validity, sets a currency adjustment clause, and includes inventory credit for unused modules.
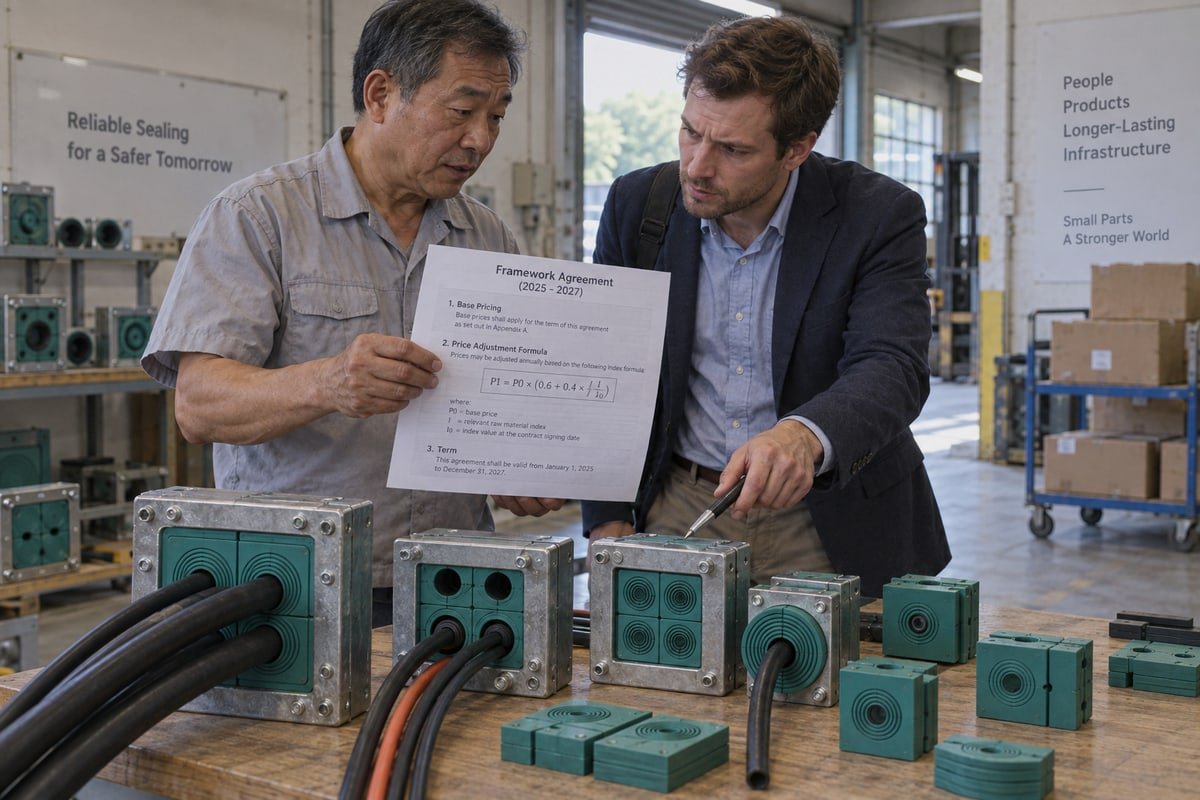
There is a real difference between price locking and price risk sharing. Price locking means the supplier absorbs every input swing. Price risk sharing means both parties agree on how a swing gets split. In my experience, pure price locking beyond 12 months either fails or gets padded. The supplier quietly adds a risk premium. You pay for certainty you may never use.
Four contract structures compared
| Structure | How it works | Where it fits |
|---|---|---|
| Fixed-price agreement | Unit price frozen for a set term, usually 12–24 months | Stable inputs, short programs, strong supplier balance sheet |
| Index-linked pricing | Base price plus adjustment tied to a steel or rubber index | Multi-year EPC projects with visible input costs |
| Threshold band | Price holds until the index moves beyond an agreed band, then adjusts | Buyers who want stability but accept large moves |
| Framework with call-offs | Volume commitment with staged POs and reserved production slots | OEM integrators building BESS containers or data center modules |
For most European integrators, I recommend the third row combined with the fourth. It keeps the price flat through normal noise and only reopens when something real happens.
A negotiation checklist that actually works
- Shorten quote validity to 30 days or less. Long validity invites drift between award and PO.
- Split the price into a base component and an escalation formula. Name the index.
- Add a currency adjustment clause with a band, so small FX moves do not trigger renegotiation.
- Negotiate payment terms that shorten the exposure window, not just the cash cycle.
- Ask for dual-currency invoicing where the supplier can support it.
- Add an inventory credit clause. Unused sealing modules return as credit on the next project.
- Keep a qualified second source in the bid so FX pass-throughs stay honest.
Bring procurement forward into FEED
The best contracts I sign are placed during front-end engineering. At that stage the buyer can standardize frame sizes across all modules, reserve production slots, and buy in bulk at current rates. Standardization also cuts variety, which means longer production runs and lower unit cost. Some teams now use digital twin simulations to calculate packing space and cable density. That removes the roughly 15% buffer stock that manual estimation usually adds. Inventory buffer management then becomes a choice, not an accident.
One objection I hear is that contract engineering makes financial hedging unnecessary. Sometimes it does. If the supplier accepts a threshold band and functional-currency invoicing, the residual exposure may be small enough to ignore. But that residual should be measured, not assumed.
How do I validate a lower-cost MCT supplier without risking certification or delivery reliability?
On our pressure test rig, TSR assemblies are held at up to 0.4 MPa before release. That report is the first thing I send a skeptical buyer.
Validate a lower-cost MCT supplier in stages: verify ISO 9001, IATF 16949, and BV factory approval; request A-0/A-60 fire, IP68, and pressure test documents; run free samples in your 120-frame cutouts; audit lead times on a pilot order; then qualify as second source.
A 40–60% lower unit price triggers suspicion in any experienced buyer. It should. The right response is not to reject it, but to test it. Here is the sequence our customers use, and the sequence I would use if I were on their side of the table.
The five-stage qualification path
- Paper check. Confirm the supplier is a factory, not a trader. Ask for the business registration, plant addresses, and quality system certificates. Our own records show a Shaanxi headquarters, additional production in Shandong and Hunan, and 38 granted patents. A trading company cannot produce that.
- Test document review. Request fire rating reports for A-0/A-60 firestop transit frames, IP68 ingress results, and watertight and gas-tight test data across the 0.01–0.4 MPa range. Read them before replying.
- Dimensional fit. Use the cross-reference table to map your existing model numbers to the alternative. Then fit free validation samples into your actual frame cutouts. Step-core halogen-free EPDM modules should seat in standard 120-frame geometry without rework.
- Pilot order. Place a small PO with a real delivery date. Measure the promised lead time against the actual one. Check packaging, marking, and export paperwork.
- Second-source qualification. Add the supplier to the approved vendor list with a defined share of volume.
What each stage protects
| Stage | Risk it removes | Evidence to keep on file |
|---|---|---|
| Paper check | Supplier disappears or subcontracts | Registration, ISO 9001, IATF 16949, BV approval |
| Test documents | Certification failure on site | Fire, IP68, and pressure reports |
| Dimensional fit | Rework and installation delay | Sample fit photos, CAD/STEP comparison |
| Pilot order | Lead time surprises | Dated PO, packing list, delivery record |
| Qualification | Single-source pricing power | AVL entry, volume split |
Design for vendor interoperability
The smartest buyers go one step further. They select frame dimensions that accept sealing inserts from more than one manufacturer. This creates a secondary supply route the moment a primary vendor raises prices. It also supports lead time optimization, because spare modules can ship from whichever plant has stock. Total cost of ownership drops not just from unit price, but from fewer stockouts and shorter downtime.
What documentation should I request to protect my procurement budget against unexpected cost escalations?
I learned this the hard way: a verbal price hold is worth nothing once the euro moves. Now every DewinMCT quote states its currency, validity, and escalation basis in writing.
Request a written quote with currency, validity date, and Incoterm; a cost breakdown separating material, labor, and freight; the index formula and adjustment threshold; certified test documents; a lead-time commitment; cross-reference drawings with STEP files; and a change-notification clause for any price movement.
Documents do not stop prices from moving. They stop prices from moving without warning. That distinction matters when a project controller asks why the MCT line jumped after budget approval. If the paperwork is complete, you can show exactly which input moved, by how much, and whether the contract allowed it.
The document set I would demand
| Document | What it protects against | Who supplies it |
|---|---|---|
| Written quote with currency, Incoterm, and validity date | Silent FX pass-through and expired pricing | Supplier sales |
| Cost breakdown by material, labor, freight, and overhead | Arbitrary increases with no traceable cause | Supplier costing team |
| Index formula and threshold band in the contract | Disputes over what counts as a legitimate adjustment | Both parties |
| Test reports for fire, IP68, and pressure sealing | Requalification costs after a failed inspection | Supplier QC |
| Lead-time commitment with a production slot reference | Expediting fees and site delays | Supplier planning |
| Cross-reference table and CAD/STEP files | Redesign cost when switching sources | Supplier engineering |
| Export documentation and certificate of origin | Duty surprises and customs holds | Supplier export desk |
| Change-notification clause with notice period | Price changes discovered at invoice stage | Contract |
Why the cost breakdown is the most important line
Buyers often skip the breakdown because suppliers resist it. Push anyway. Without it, raw material price indexation 4 cannot work, because you cannot tell which share of the price is steel, which is EPDM compound, and which is labor. With it, the index formula becomes simple arithmetic. If steel is 35% of the module cost and the steel index rises 10%, the adjustment is 3.5%, not whatever the supplier feels like charging.
Documentation as part of strategic sourcing partnerships
The best long-term supplier relationships I have are the ones where the paperwork is boring. Both sides know the formula. Both sides know the notice period. Nobody argues at invoice time. That is what strategic sourcing partnerships should feel like. For OEM integrators running private-label programs, I also recommend a documented mold ownership clause and a spare-parts price list valid for the same term as the frame agreement. Spare sealing modules are where surprise costs usually hide, because they are ordered late and in small quantities. Fixing their price early closes the last gap in the budget.
Conclusion
Volatile FX and steel will keep attacking MCT budgets. Map the exposure, contract the formula, hedge the residual, and qualify a certified second source. Then the budget holds.
Footnotes
1. Technical definition and overview of modular cable sealing systems. ↩︎
2. Institutional guide to standard engineering, procurement, and construction contract structures. ↩︎
3. Technical reference for the synthetic rubber material used in cable sealing modules. ↩︎
4. Authoritative source for trade and customs regulations affecting material cost indexing. ↩︎



 English
 Español de México
 Deutsch
 Français
 العربية
 Русский