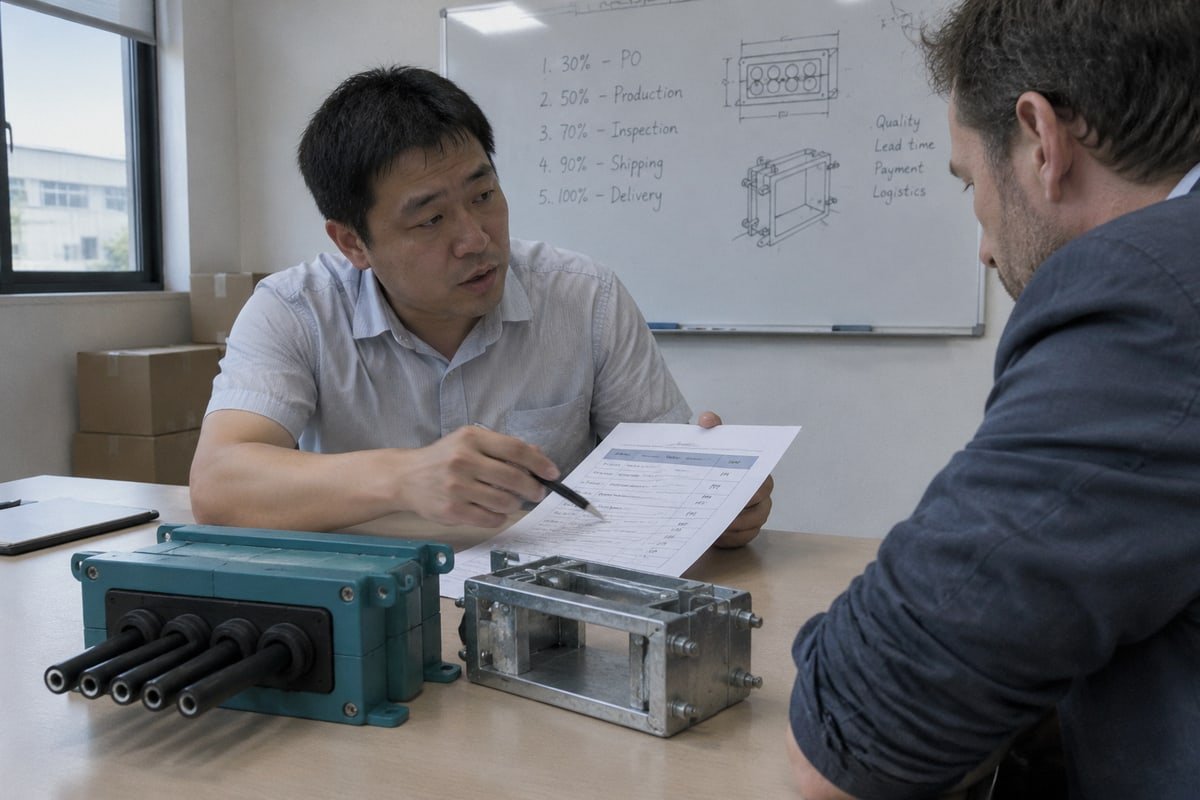
Advance payment and final payment terms for MCT systems can stall a good deal galvanized steel 1. I have watched buyers lose weeks over a deposit clause. Our export team negotiates structure first.
Negotiate advance payment and final payment terms for MCT systems as a milestone payment schedule: a capped 20–30% deposit released against a proforma invoice or bank guarantee, progress billing at factory acceptance testing, and a final balance tied to written acceptance criteria, test reports, and shipping documents.
The percentages matter less than the triggers behind them. Below, I walk through each stage of the schedule. I use the same numbers we see in real tender templates and the same documents we hand over from our own test bench.
What Advance Payment Percentage Is Reasonable for MCT Cable Transit Orders?
A sourcing manager in Germany once asked me why our proforma showed 30% upfront when his EPC template capped advances at 15%. That gap is where most negotiations start.
A reasonable advance for MCT cable transit orders sits between 10% and 30% of contract value. Standard catalog modules justify 10–20%; custom frames or private-label molds justify 20–30%. Public procurement often caps advances at 15%, and buyers can demand a bank guarantee before release.
The right number depends on what the deposit actually pays for. So I always break the advance into its parts before I defend it.
What the deposit funds on our line
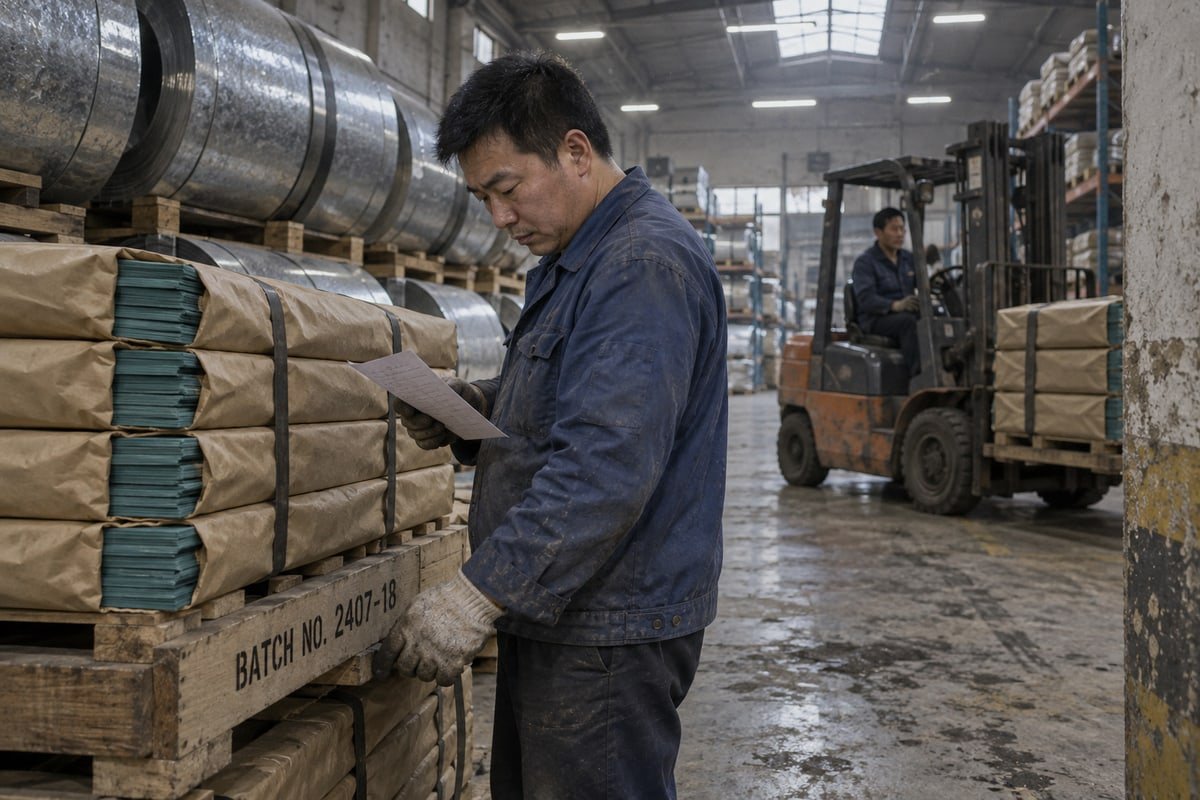
For a standard TSC square module or TSR round seal, the early spend is halogen-free EPDM compound 2 and galvanized steel for the frame. We buy both before the press runs. For a custom size, our in-house mold shop cuts the tooling first. That tooling is the honest reason a higher advance is fair on a custom job. Procurement lead times for the rubber compound are also longer than the molding cycle itself. The deposit bridges that gap. If the advance is zero, someone still finances the compound for those weeks. That cost then moves into the unit price.
Benchmarks buyers can quote back to us
| Source of the benchmark | Advance figure | Condition attached |
|---|---|---|
| Public procurement contract | Up to 15% of contract price | Documentary requirements before release |
| Project RFP | 10% advance | Bank guarantee equal to 110% of the advance |
| Solar thermal contract template | Deposit capped at 25% | Deposit plus further advance may not exceed 60% upfront |
| Current market practice for MCT orders | 20–30% | Offsets frames and halogen-free sealing inserts bought early |
| Common retention pairing | 5–10% held back | Released after site integration test or warranty period |
These figures are not universal. They show the range that both sides can defend without sounding unreasonable.
How I counter a cap without losing the order
When EPC project procurement rules cap the advance at 15%, I do not fight the cap. I add a second progress billing point at factory acceptance testing instead. That keeps our cash flow workable and keeps the buyer's upfront exposure inside policy. A buyer will often push back: "Why should I fund your material purchase?" My answer is simple. A 10–20% advance on cable penetration seals 3 is cheaper for the buyer than a fully financed price. It also lets us reserve press time for the order. For drop-in replacement modules in common 120-frame sizes, I can go lower, because we hold compound in stock. For custom molds, I hold closer to 30% and show the tooling cost line by line.
How Do I Protect My Company If I Pay a Deposit Before Production Starts?
Every deposit clause forces a trade-off on our side: accept bank guarantee costs and win the order, or hold firm on unsecured cash and risk losing it.
Protect a pre-production deposit by keeping it small and secured: request an advance-payment bank guarantee or irrevocable Letter of Credit, verify the factory's legal registration and certifications, obtain free validation samples first, and write refund triggers for missed delivery dates directly into the contract.
A deposit is only risky when it is blind. I recommend that buyers follow a short process before any money moves. It is the same process our better customers already use on us.
A five-step due diligence sequence
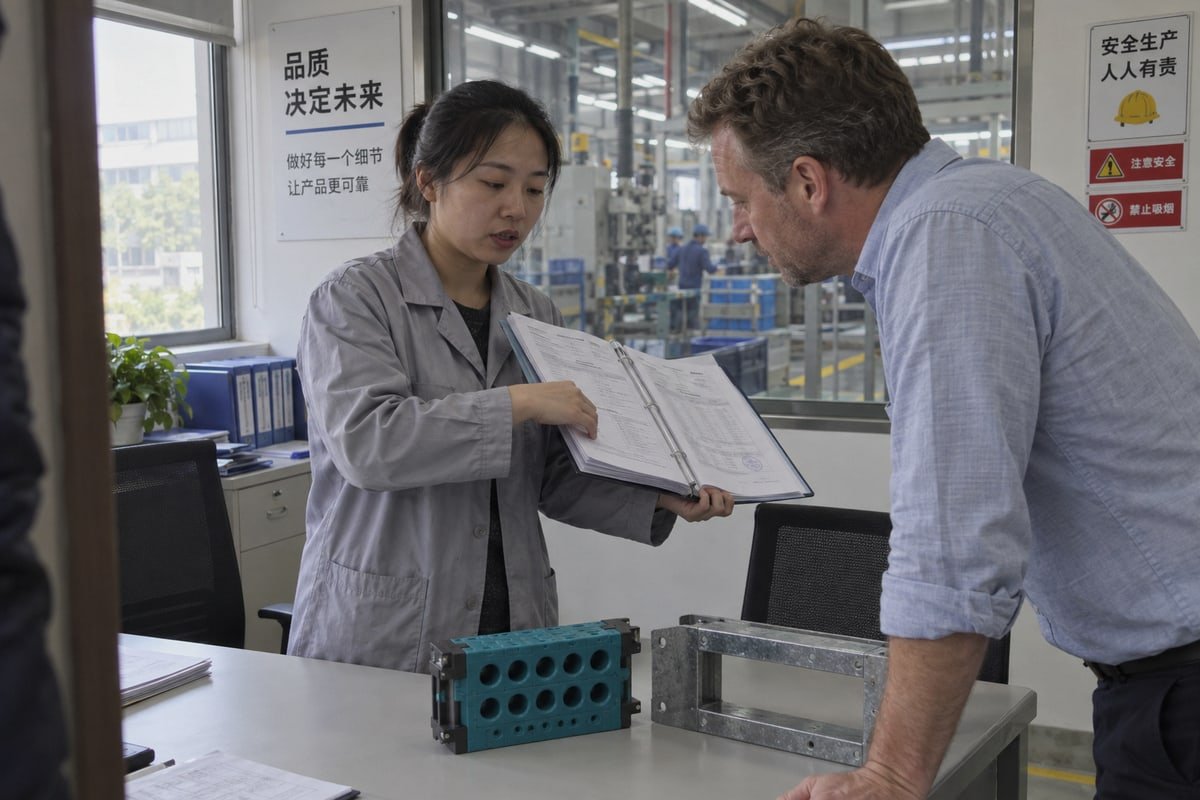
- Verify the legal entity. Ask for the business license, registered capital, and factory address. We share ours openly: a Shaanxi headquarters, production sites in Shandong and Hunan, RMB 50M registered capital, and an operating history since 2013. A trading company cannot show a press floor.
- Check the quality system, not the brochure. Request the ISO 9001 and IATF 16949 certificates and the BV factory approval. Then check the certificate numbers with the issuing body.
- Test before you pay. Our free validation samples exist for this reason. A buyer fits a sample TSC module into an existing 120-frame cutout, checks the step-core fit against the cross-reference table, and only then places a deposit.
- Pick a security instrument. Match the instrument to the order size and the country. The table below compares the common options.
- Write the refund trigger. State the exact delivery date, the grace period, and the refund route if we miss it.
Comparing security instruments for the advance
| Instrument | Who bears the cost | Buyer protection level | Best fit |
|---|---|---|---|
| T/T with advance-payment bank guarantee | Seller pays the guarantee fee | High; funds recoverable on default | Mid-size orders, first-time suppliers |
| Irrevocable Letter of Credit 4 | Buyer pays issuance; seller pays confirmation | High; funds released only against documents | International orders, new relationships |
| Third-party escrow | Shared or buyer | High for the final balance | Commissioning-linked final payments |
| Plain T/T deposit, no security | Nobody upfront | Low; relies on supplier reputation | Repeat orders with proven history |
The objection I hear most
Buyers say: "You will price the guarantee fee back into my quote." That is partly true. A bank guarantee costs us money, and I do not hide it. But the fee is small next to the cost of an unsecured deposit going wrong. The better compromise is often a smaller advance without a guarantee, plus a Letter of Credit for the balance. A buyer's exposure then stays under the 25% deposit cap that many contract templates already use.
Can I Negotiate Final Payment After Receiving Test Reports and Validation Samples?
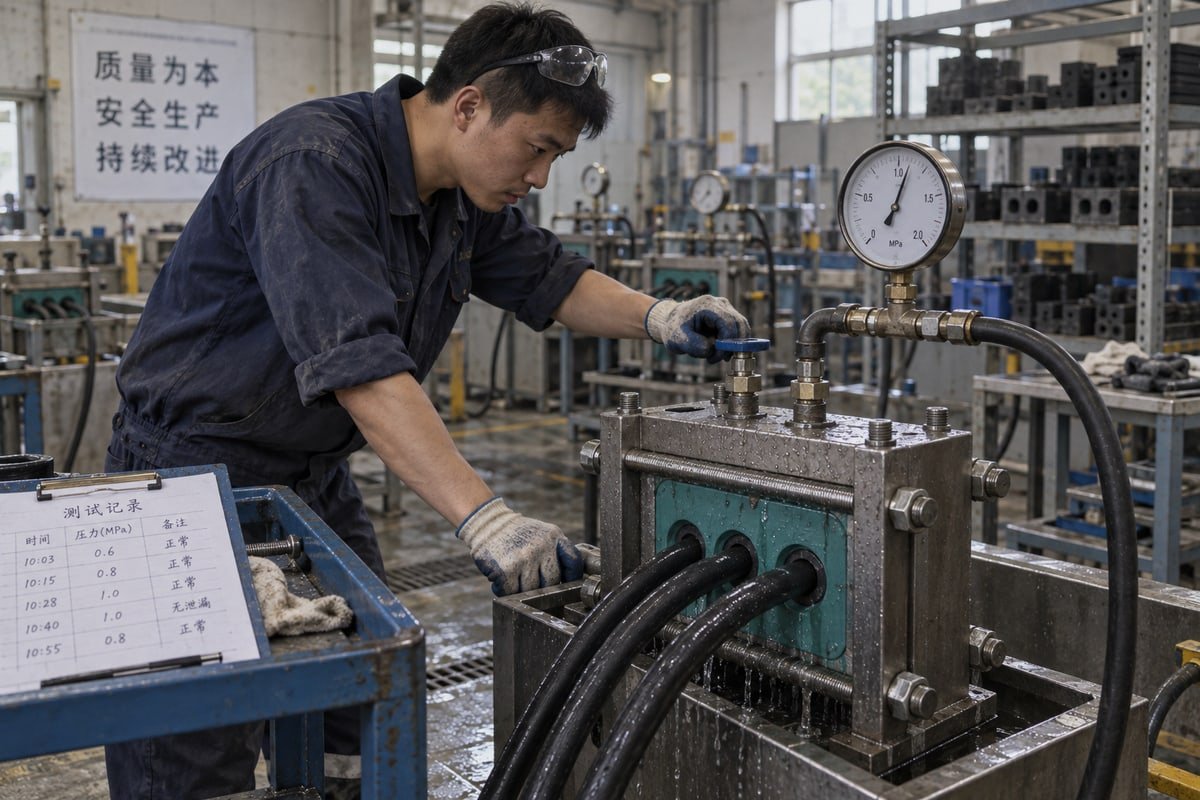
Last spring our QC bench held a TSC module at 0.4 MPa for its gas-tight check while the buyer's inspector watched over video. That footage became his final payment trigger.
Yes. Final payment can be tied to delivered test reports and validated samples, but only if the contract defines acceptance objectively: named test standards, pass thresholds such as IP68 or A-60, a review window, and a punch-list rule so minor cosmetic issues cannot block release.
Final payment is where most disputes happen. Not because anyone is dishonest, but because "acceptance" was never written down. I now insist on a document list before we sign.
Which documents can trigger which payment
| Document or event | What it proves | Payment it can release |
|---|---|---|
| Validation sample sign-off | Dimensional fit in the buyer's existing 120-frame cutout | Confirms the order; unlocks the advance |
| Factory acceptance test report | Watertight and gas-tight sealing across 0.01–0.4 MPa | Progress billing at FAT |
| Fire rating certificate (A-0 / A-60) and IP68 report | Compliance with the specified rating | Condition for final balance |
| Bill of lading and packing list | Goods shipped as ordered | Final balance under a Letter of Credit |
| Site integration test or warranty expiry | Field performance | Release of retention money |
Retention money as the middle ground
A common buyer position is: "I will not pay the final balance until the system is installed and proven on site." I understand this. But a factory cannot control the installer's torque on the compression unit or the cable spacing in the stay plates. So I propose retention money instead. The buyer pays the balance against shipping documents. A 5–10% retention is held until the site integration test or the end of the initial warranty period. The buyer keeps leverage for defects. We receive most of the contract value on time. A third-party escrow account for that retention makes the arrangement cleaner for both sides.
Fixing the vague clause
The clause "final payment after acceptance" invites argument. I rewrite it like this: final payment falls due 14 days after the buyer receives the FAT report, fire certificate, IP68 report, and shipping documents, unless the buyer issues a written non-conformance notice within that window. Cosmetic marks on a rubber module that still passes pressure test do not count as non-conformance. That one sentence has saved more time than any discount. Some buyers also ask for a small early payment discount if they settle within the window. I am open to that, because a fast, undisputed close is worth more than the margin.
What Payment Terms Do Established MCT Manufacturers Typically Accept for Long-Term Contracts?
The lesson from our first multi-year frame agreement was simple: annual volume forecasts earned the buyer better vendor credit terms than any single hard-fought discount.
Established MCT manufacturers usually accept 30% advance with 70% against shipping documents for first orders, then move long-term partners toward Letter of Credit at sight, 10–20% deposits, blanket-order call-offs, and net 30–60 day vendor credit terms once payment history and volumes are proven.
Payment terms are financing terms. A long-term contract lets both sides finance less. I structure the progression in stages, and I tell buyers upfront what unlocks the next stage.
How terms improve as the relationship matures
| Relationship stage | Advance | Balance | Extra protections |
|---|---|---|---|
| First order (qualification) | 30% T/T | 70% against B/L copy or LC at sight | Free validation samples; FAT report; full test documents |
| Qualified second source | 10–20% T/T | Balance against documents | 5% retention money; fixed spare-module lead time |
| Framework agreement with forecasts | 0–10% on call-off | Net 30–60 days from invoice | Price escalation clause; annual review; supply chain financing 5 option |
The move from the first row to the third is earned. Clean payment history and steady call-offs are what justify open credit on our side.
Protecting the value of the final payment
A buyer objection on multi-year deals is: "A fixed price locks me in, and a fixed price locks you in too. Who absorbs a steel spike?" I prefer a price escalation clause tied to a named steel or polymer index. It is fair in both directions. Frame steel and EPDM compound are our two largest inputs, so the clause tracks the real cost. Some buyers also propose supply chain financing through their bank. That lets us receive funds early while the buyer pays on net 60. I welcome it, because it lowers the pressure to ask for a higher advance.
Newer mechanics, and where I stay cautious
Three ideas come up in recent negotiations. First, escrow for the final balance, released at commissioning. This works well and I accept it. Second, smart-contract style triggers, where a digital pressure test log or delivery scan releases payment automatically. The idea is sound, but the trigger data still has to come from an agreed test procedure, so the contract language matters more than the software. Third, performance-based final bonuses if the system exceeds a fire or water-tightness rating. I push back gently here. An A-60 rating or IP68 result is pass or fail. There is no "exceeding" it in a meaningful way. A retention release tied to a clean site test is a cleaner tool for the same goal. Getting advance payment and final payment terms for MCT systems right on a long-term contract is about matching money to verifiable events, not about adding clever clauses.
Conclusion
Unclear payment terms stall MCT orders and erode trust. Fix the structure: cap and secure the advance, define acceptance in writing, then earn better terms through repeat volume.
Footnotes
1. The World Steel Association is the international body representing steel producers and material standards. ↩︎
2. ASTM International develops the technical standards for materials like EPDM rubber used in industrial seals. ↩︎
3. The International Maritime Organization (IMO) sets global safety standards for fire-safe cable penetration seals. ↩︎
4. The International Chamber of Commerce (ICC) establishes the global rules for documentary credits and trade finance. ↩︎
5. The World Bank Group provides comprehensive resources on international trade finance and supply chain financing structures. ↩︎



 English
 Español de México
 Deutsch
 Français
 العربية
 Русский